The federal government announced significant updates to Canada’s mortgage insurance rules on November 6, 2026, aimed at accelerating the construction of triplexes, fourplexes, and larger multi-unit residential buildings.
These policy shifts, effective February 1, 2027, remove long-standing financial barriers for developers by eliminating property value ceilings and owner-occupancy mandates for new multiplex projects.
Launch Len Media views these adjustments as a vital catalyst for the missing middle housing supply, though the long-term impact on overall affordability remains a subject of intense debate among market analysts.
The New Rules for Multiplex Financing
The federal government’s 2026 budget introduces a major shift in how lenders and insurers approach multi-unit residential developments. Starting February 1, 2027, the government will remove the $1.5-million property value ceiling for new triplexes and fourplexes. Source: Government of Canada.
Additionally, the requirement for owners to reside in one of the units within these properties will be eliminated. This change allows developers to build and rent out all units in a project while still qualifying for government-backed mortgage insurance.
Insured loans for these new developments will be permitted to cover up to 90 percent of the property’s expected value upon completion. This applies to both the construction phase and the purchase of newly completed properties.
The policy also extends to larger multi-unit residential properties containing between five and 50 units. Private mortgage insurers are now authorized to cover these projects, providing developers with more options for financing construction, purchases, and renewals.
Mechanics of the Amortization and Debt Requirements
For properties containing five to 50 units, the new rules allow for amortization periods of up to 50 years for new construction. This extended timeline is intended to lower monthly debt service costs for developers, making projects more financially viable.
For other types of loans involving these larger properties, the maximum amortization is capped at 40 years, with loan-to-value limits set at 85 percent. These rules exclude construction loans, which will be assessed based on individual insurer criteria.
Borrowers must meet specific financial thresholds to qualify for these insured products. This includes maintaining a net worth of at least 25 percent of the requested loan amount, with a minimum of $100,000 in assets held within Canada.
The property must also generate sufficient income to cover debt payments. Specifically, the building’s net income after operating expenses must cover at least 115 percent of debt payments for a five-year mortgage term, or 110 percent for a 10-year term.
Standard stress test requirements remain in place for individual borrowers. For completed triplexes and fourplexes, housing costs cannot exceed 39 percent of gross income, and total debt payments must remain under 44 percent of gross income.
Key Financing Options for Developers
The changes provide several paths for developers to secure funding for missing middle housing. These options are designed to align with the evolving needs of the Canadian housing market. Source: Daily Hive.
For a $3-million fourplex, which previously exceeded the $1.5-million insurance limit, a developer can now theoretically obtain an insured loan of up to $2.7 million. This represents a 90 percent loan-to-value ratio, significantly reducing the upfront capital required.
Developers can choose to rent out all units in a triplex or fourplex under an insured mortgage with a 30-year term. Alternatively, they may sell the units individually to buyers, providing flexibility in project exit strategies.
For larger multi-unit residential properties, developers can access 50-year amortization periods for new construction. This helps manage cash flow during the early years of a rental project, which is critical for long-term sustainability.
The removal of the owner-occupancy requirement is a significant shift for small-scale developers. It enables the creation of purpose-built rental housing on lots that were previously restricted to single-family homes.
- Triplex and fourplex projects: Eligible for 90% insured financing with no property value cap.
- Purpose-built rentals: Owners no longer required to live on-site, facilitating pure rental developments.
- Five-to-50-unit buildings: Private insurers can now cover construction and refinancing for these larger projects.
- Extended amortization: New rental construction can now qualify for up to 50-year repayment periods.
- Construction loans: Insurers will use internal criteria to assess repayment ability, bypassing standard debt-payment ratios.
Analysis of the Policy Impact
The federal government’s decision to ease mortgage insurance rules is a direct response to the financing hurdles that have long plagued small-scale residential developments. By treating multiplexes as residential rather than commercial assets, the government is attempting to lower the barrier to entry for smaller builders.
Launch Len Media believes this is a necessary step to address the missing middle housing supply. Traditional lenders often view multiplexes as high-risk commercial projects, which requires higher down payments and stricter qualification standards that many small developers cannot meet.
However, critics point out that these changes do not address the root causes of the housing crisis. High construction costs, municipal zoning delays, and the fundamental supply-demand imbalance remain significant obstacles that mortgage insurance alone cannot fix.
The Bank of Canada has previously cautioned that mortgage rule adjustments are not a magic fix for affordability. While these changes will likely increase the number of projects that qualify for financing, they may not result in immediate price reductions for consumers.
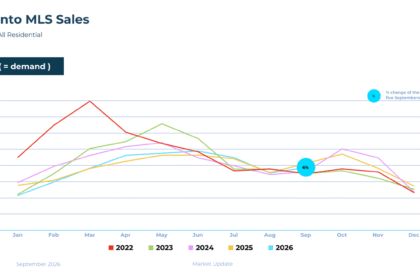
Despite these criticisms, the policy remains a vital tool for increasing density in urban areas. By aligning financing options with the goal of creating more homes on existing lots, the government is creating a more conducive environment for developers to build. Source: Toronto Regional Real Estate Board.
The federal government’s Spring 2026 economic update, which first hinted at these forthcoming mortgage insurance policy changes, acknowledged that builders still struggled to borrow at rates that made smaller projects viable.
Government of Canada
What Developers and Investors Can Do
If you are a developer or investor looking to capitalize on these changes, start by reviewing your current project pipeline. Evaluate whether your upcoming triplex or fourplex developments meet the new criteria for insured financing.
Consult with your mortgage broker or lender to understand how the new 90 percent loan-to-value ratio will affect your project’s pro forma. You may find that projects previously deemed unfeasible due to high down payment requirements now pencil out.
Ensure your financial records are in order, particularly regarding your net worth and asset documentation. Since lenders will require proof of at least $100,000 in Canadian assets for larger multi-unit projects, early preparation is essential.
Stay informed about municipal zoning changes in your area. While federal financing is now more accessible, you still need to secure the necessary permits to build triplexes or fourplexes on your chosen lots.
Consider the long-term rental income potential of your projects. With the removal of the owner-occupancy requirement, you can now focus on developing purpose-built rental housing that provides stable, long-term cash flow.
Frequently Asked Questions
When do the new mortgage insurance rules take effect?
The new mortgage insurance rules for triplexes, fourplexes, and larger multi-unit residential properties take effect on February 1, 2027.
Do I still need to live in one of the units to qualify for insurance on a triplex?
No, the requirement for owners to reside in one of the homes has been removed for eligible new triplexes and fourplexes.
What is the maximum amortization period for new multi-unit rental construction?
Newly constructed rental properties with five to 50 units may qualify for amortization periods of up to 50 years.