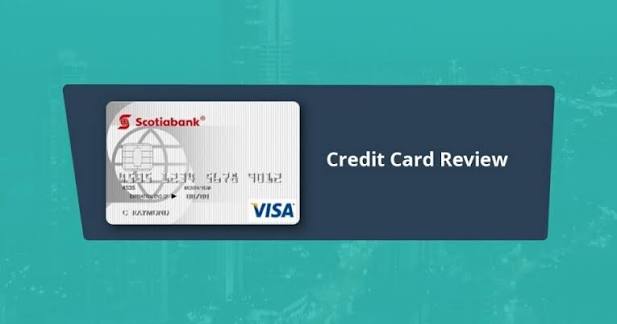
The Scotiabank Value Visa provides a specialized financial instrument for Canadians seeking to manage high-interest debt through a lower-than-average interest rate of 13.99%. New accounts opened between July 2, 2026, and January 3, 2027, also benefit from a 0% introductory balance transfer rate for nine months.
For those struggling with mounting interest charges, this card serves as a tactical utility rather than a lifestyle product. Launch Len Media views this card as an effective bridge for debt repayment, provided the user avoids the traps of high-interest penalties and understands the lack of long-term rewards.
The mechanics of the interest rate advantage
The primary appeal of the Scotiabank Value Visa is its 13.99% interest rate on purchases and cash advances. According to data from Savvy New Canadians, this rate sits well below the typical Canadian credit card average of 20% to 21%.
This lower rate is intended to help cardholders reduce the total interest paid on outstanding balances over time. For a consumer carrying a $5,000 balance with monthly payments of $250, the difference in interest costs compared to a 21.99% card can exceed $500 over the life of the debt.
The card also includes access to the Scotia SelectPay program. This feature allows cardholders to convert purchases of $100 or more into fixed installment plans, providing further control over repayment schedules.
However, these benefits are strictly tied to account standing. As noted by Ratehub.ca, the card offers no rewards, no insurance coverage, and no cash back, which limits its utility for everyday spending.
The Scotiabank Value Visa is a card that specializes in chipping away at credit card debt with its low purchase interest rate and helpful balance transfer offer.
NerdWallet Canada
Navigating the nine month balance transfer window
New accounts opened before January 3, 2027, are eligible for a 0% interest rate on balance transfers for nine months. This offer carries a 1% transfer fee, which is a standard cost for moving debt between institutions.
The strategy for success involves aggressive repayment during this nine-month period. If a user transfers $1,000, they would need to pay approximately $113 per month to clear the balance before the promotional period expires.
Once the nine-month window closes, any remaining balance reverts to the standard 13.99% rate. It is essential for users to calculate their monthly capacity to pay down the principal to ensure they do not carry debt into the higher-interest phase.
Existing Scotiabank customers who switch to this card are generally ineligible for the promotional balance transfer offer. The bank applies this policy to prevent users from simply shifting debt internally without new credit acquisition.
Alternatives for debt consolidation
When evaluating the Scotiabank Value Visa, consumers should compare it against other low-rate options available in the market. Each alternative offers different trade-offs regarding fees and promotional durations. Source: Savvy New Canadians.
The RBC Visa Classic Low Rate Option features a lower interest rate of 12.99% and a $20 annual fee. While the rate is more competitive, the balance transfer and cash advance rates are higher at 14.99%.
The MBNA True Line Mastercard provides a 0% introductory interest rate for 12 months, which is three months longer than the Scotiabank offer. However, it carries a higher balance transfer fee of 3% and lacks an annual fee.
The BMO Preferred Rate Mastercard is another option for those focused on long-term debt management. It offers a 0% introductory rate on balance transfers for 18 months, though it also includes a 3% balance transfer fee.
- RBC Visa Classic Low Rate: Best for a slightly lower purchase interest rate of 12.99%.
- MBNA True Line Mastercard: Offers a longer 12-month promotional period with no annual fee.
- BMO Preferred Rate Mastercard: Ideal for those needing a longer 18-month window for balance transfers.
- Scotiabank Value Visa: Best for those who prefer a shorter 9-month window with a lower 1% transfer fee.
The penalty for missing payments
The low interest rate on the Scotiabank Value Visa is conditional. According to terms outlined by Scotiabank, missing two consecutive minimum payments results in the immediate loss of the preferred rate.
In such cases, the interest rate on purchases jumps to 24.99% and the rate on cash advances increases to 27.99%. These rates are significantly higher than the standard market average.
This penalty structure highlights the importance of setting up automated payments or calendar reminders. For a consumer already struggling with debt, the jump to 24.99% can quickly negate any savings achieved through the initial lower rate.
The financial impact of these penalties is severe. It effectively punishes the cardholder for the very behavior that the card is intended to help them manage.
Strategic analysis for the modern consumer
The Scotiabank Value Visa is a niche product. It succeeds as a debt management tool but fails as a primary credit card for those who pay their balances in full. Source: Ratehub.ca.
Critics might argue that the $29 annual fee makes it less attractive than no-fee alternatives. However, the interest savings on a significant balance often outweigh the cost of the fee in the first year.
Launch Len Media maintains that the value of this card is found in its discipline. It forces the user to focus on repayment rather than spending, which is a critical step in managing canadian household credit effectively.
The fair counterpoint is that the lack of rewards makes it a dead-end card. Once the debt is cleared, the user should consider transitioning to a rewards-based card to maximize their spending power.
Steps to take before you apply
Before applying for the Scotiabank Value Visa, calculate your total debt and determine if you can realistically pay it off within the nine-month promotional window.
Review your current credit card statements to identify if the interest savings will exceed the $29 annual fee. If your balance is low, the interest savings may not justify the cost of the card.
Ensure you have a plan to make consistent payments. Missing two payments will trigger the penalty rates, which will make your debt situation worse than it was before.
Check if you are eligible for the balance transfer offer. Existing Scotiabank customers should contact the bank to confirm if they qualify for the promotional terms before initiating a switch.
Frequently Asked Questions
Is the Scotiabank Value Visa good for everyday spending?
No, it is not ideal for everyday spending because it offers no rewards, cash back, or points. It is designed specifically for debt consolidation.
What happens if I miss a payment?
Missing two consecutive minimum payments will cause your interest rate to increase to 24.99% on purchases and 27.99% on cash advances.
Can I use the balance transfer offer if I am already a Scotiabank customer?
Generally, no. Existing Scotiabank customers who switch to this card are usually ineligible for the promotional balance transfer offer and the first-year annual fee waiver.
Related coverage on LaunchLen Media: Why Lines of Credit Are Risky During Economic Instability.