Telus Corporation reported a $660 million net loss for the third quarter of 2026, driven by an $800 million non-cash goodwill impairment charge within its Telus Health division. This significant write-down marks a pivotal moment for the company as it navigates an unsolicited takeover bid from Quebecor Inc.
The impairment underscores the failure of the company’s aggressive diversification strategy, forcing a pivot back to core telecom operations. Investors must now weigh the long-term value of the remaining assets against the potential for a major corporate restructuring.
The Mechanics of the Impairment Charge
The $800 million impairment charge recorded in the third quarter of 2026 reflects a stark adjustment to the valuation of the Telus Health unit. According to company filings, this charge was driven by updated growth expectations and valuation adjustments related to an active divestiture process. Source: The Globe and Mail.
While the loss is categorized as non-cash, it significantly impacted the bottom line, resulting in a quarterly net loss of $660 million. This development follows a period of intense expansion where the company sought to capitalize on digital health integration.
Consolidated service revenue for the quarter fell 1% year-over-year to $4.5 billion, indicating that the core business is facing headwinds alongside the challenges in its secondary divisions. The company’s reliance on these non-core assets has created a drag on overall financial performance.
Despite these pressures, the core telecom business remains robust. Mobile phone churn reached a three-year low of 1.01% during the third quarter, demonstrating that the company retains a strong grip on its primary subscriber base.

Quebecor and the Takeover Landscape
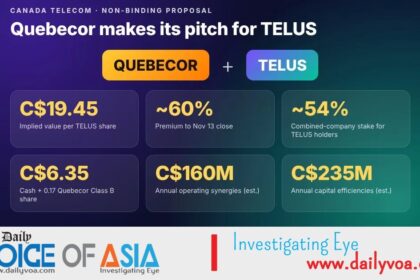
On November 16, 2026, the market landscape changed dramatically when Quebecor Inc. announced an unsolicited acquisition proposal for Telus. The offer is valued at approximately CAD 19.45 per share, representing a significant premium over recent trading levels.
The announcement triggered a 25.4% surge in Telus stock during pre-open trading, as investors reacted to the prospect of a potential consolidation. This bid forces the board to evaluate whether the company is better off as a standalone entity or as part of a larger telecommunications conglomerate.
The timing of the bid is critical, as it arrives while Telus is already in the midst of a strategic pivot. The company must now balance its internal efficiency programs against the external pressure of a takeover attempt.
Shareholders are currently in a holding pattern as they await official responses from the Telus board regarding the viability of the Quebecor proposal. The outcome will likely dictate the company’s capital allocation strategy for the next several years.
The impairment charge was attributed to updated growth expectations and valuation adjustments related to the company’s active divestiture process.
PR Newswire
Strategic Options for Shareholders
Investors facing the current volatility have several paths to consider as the company navigates its restructuring and potential acquisition. The focus remains on whether the company can successfully execute its efficiency program while managing the fallout from its recent health unit write-downs. Source: TELUS.
These options represent the primary avenues for managing exposure to Telus during this period of transition:
1. Hold for the potential acquisition premium: Investors may choose to maintain their positions in anticipation that the Quebecor bid forces a higher offer or a competitive bidding war.
2. Monitor the $900 million efficiency program: The company’s plan to achieve $900 million in annualized cash savings by 2028 is a key indicator of its ability to restore profitability without relying on non-core growth.
3. Focus on core telecom stability: With mobile churn at a three-year low of 1.01%, the underlying business remains a cash-flow generator, which provides a level of downside protection.
4. Evaluate the divestiture progress: The ongoing sale of non-core assets is intended to clean up the balance sheet, which may unlock shareholder value regardless of whether a takeover succeeds.
Analysis of the Pivot
LaunchLen Media argues that the Telus Health impairment underscores the failure of the company’s aggressive diversification strategy, forcing a pivot back to core telecom operations. The attempt to become a digital health powerhouse created significant balance sheet bloat that the market is now punishing.
A fair counterpoint is that the impairment is a non-cash accounting adjustment that allows the company to clean up its balance sheet and focus on high-value asset monetization. By writing down these assets, management is clearing the path to focus on core infrastructure and potentially unlocking shareholder value through the ongoing divestiture process.
The view that the pivot is necessary still holds because the core telecom business remains the company’s primary competitive advantage. Relying on high-margin, stable mobile and data services is a more sustainable strategy than the capital-intensive expansion into digital health services. Source: The Globe and Mail.
Ultimately, the market will judge the company based on its ability to generate consistent free cash flow. The current transition period is painful, but it is a necessary step to align the company’s structure with its most profitable operations.
What Readers Can Do
If you are a current shareholder, review your cost basis and determine if your investment thesis remains tied to the core telecom business or the potential for a takeover. The volatility following the impairment report and the subsequent takeover bid suggests that short-term price swings will continue.
Monitor the official filings from the Telus board regarding the Quebecor proposal. Any rejection or acceptance of the bid will have immediate and significant impacts on the stock price.
Track the company’s progress on its $900 million efficiency program. If the company fails to meet these savings targets, the pressure on the balance sheet will likely increase, regardless of the outcome of the takeover bid.
Consider the stability of the mobile subscriber base as your primary metric for long-term health. As long as churn remains low, the company maintains a strong foundation for future cash generation.
Frequently Asked Questions
Why did Telus report such a large loss in Q3 2026?
The loss was primarily driven by an $800 million non-cash goodwill impairment charge related to the Telus Health division, which reflects lower growth expectations for that unit.
What is the status of the Quebecor acquisition bid?
Quebecor submitted an unsolicited proposal on November 16, 2026, valuing Telus at approximately CAD 19.45 per share. The company is currently evaluating this offer.
How does the efficiency program affect the company’s outlook?
The program targets $900 million in annualized cash savings by the end of 2028, which is intended to streamline operations and improve the company’s financial position following recent write-downs.