Canadian home sales fell 10.6% in October 2026, totaling 37,827 units as higher borrowing costs suppressed buyer activity. This decline follows a significant monetary policy shift by the Bank of Canada.
The cooling of the canada housing market reflects a broader struggle to balance inflation control with economic stability. Investors must now navigate a period where high interest rates dictate property valuations and transaction volumes.
The October Sales Contraction
The national real estate sector faced a sharp downturn in October 2026, with sales volume sliding 10.6% compared to the same month in 2025. Data from the Canadian Real Estate Association confirms that only 37,827 units changed hands during the period.
This contraction occurred against the backdrop of the Bank of Canada announcing a 25 basis point rate hike on October 28, 2026. This move brought the benchmark interest rate to 2.50%, marking the first increase since July 2023.
The central bank cited persistent inflation and rising energy costs as the primary justifications for the tighter monetary policy. These factors have directly influenced the cost of capital for prospective homeowners and investors alike.
Despite the annual decline, seasonally adjusted sales data showed a marginal increase of 0.3% on a month-over-month basis. This suggests that while the market is under pressure, it has not entered a state of total collapse.

Price Trends and Inventory Growth
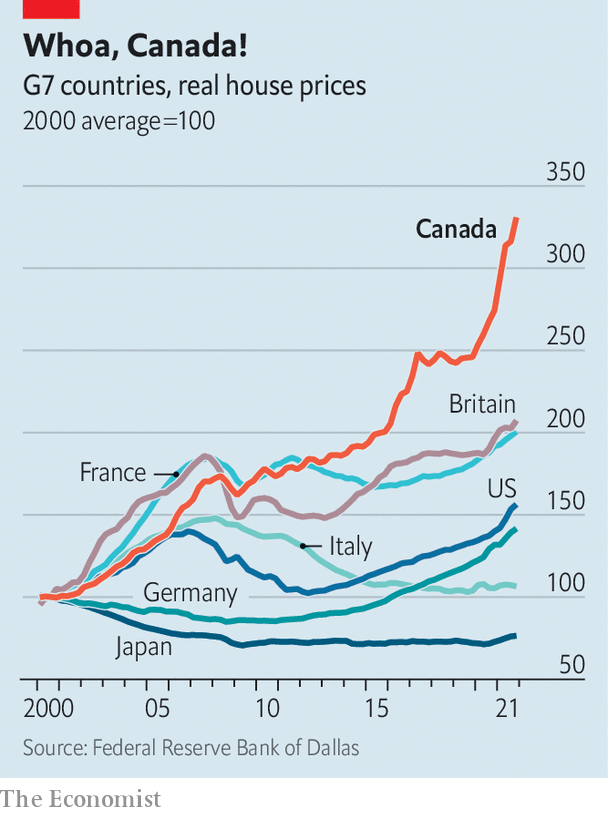
The national average home price reached $678,584 in October 2026, representing a 1.6% decrease from October 2025. While this decline is notable, it remains relatively modest given the rapid rise in borrowing costs over the same period.
RBC Economics reports that national inventory levels have reached a five-month supply. This is the highest level of available housing stock recorded since April 2026, indicating a shift toward a more balanced market.
The increase in inventory provides a potential buffer against extreme price volatility. As supply accumulates, sellers may face greater pressure to adjust their expectations to meet the current financial reality of buyers.
For those monitoring the market, the relationship between inventory and sales volume will be critical in the coming months. A sustained increase in supply without a corresponding rise in demand could lead to further downward pressure on prices.
Strategic Options for Market Participants
Investors and prospective buyers currently face a complex environment where traditional strategies may require significant adjustment. The following options highlight how participants are responding to the current economic climate.
Fixed-rate mortgage products remain a popular choice for those seeking to mitigate the risk of further rate hikes. By locking in current rates, buyers can stabilize their monthly housing costs despite the volatility in the broader economy.
Wait-and-see approaches have become increasingly common among first-time buyers who are waiting for further price corrections. With inventory at a five-month high, these buyers are positioned to act if prices continue to soften in early 2027.
Real estate investment trusts focused on rental properties are another avenue for those looking to maintain exposure to the sector. These vehicles allow investors to benefit from rental demand, which remains strong due to high population growth, without the direct burden of mortgage interest rate fluctuations. Source: RBC Economics.
- Lock in fixed-rate mortgages to hedge against future central bank rate increases.
- Monitor regional inventory levels to identify markets where supply is outpacing demand.
- Focus on rental-heavy residential assets to leverage strong population growth trends.
- Maintain higher cash reserves to capitalize on potential price dips in the coming year.
Economic Resilience Versus Monetary Headwinds
The current market trajectory suggests a tug-of-war between restrictive monetary policy and underlying economic fundamentals. While the Bank of Canada’s rate hike serves as a necessary intervention to curb inflation, it acts as a significant headwind for housing demand.
Some analysts argue that the market’s resilience is supported by robust population growth and a stable labour market. These factors provide a floor for demand that prevents a more severe correction in property values.
LaunchLen Media maintains that the current cooling is a healthy, albeit painful, adjustment. By suppressing excessive demand, the central bank is attempting to prevent a long-term inflationary spiral in the housing sector.
The counterpoint remains that if the central bank overshoots its target, the resulting economic slowdown could trigger a deeper decline in property values. However, the current data suggests that the market is absorbing these shocks with relative stability.
While the market showed little momentum, an improving labour market and population growth may support a modest recovery in 2027.
RBC Economics
Steps for Navigating the Current Market
If you are currently in the market, your first step should be to re-evaluate your financing capacity under the new 2.50% benchmark rate. Contact your lender to understand how the recent hike impacts your pre-approval status and monthly payment obligations.
Review your local market inventory data to determine if you are in a buyer’s or seller’s market. High inventory levels in your specific area may provide you with more leverage during price negotiations than the national average suggests.
Consult with a financial advisor to ensure your real estate holdings align with your long-term risk tolerance. Given the potential for further rate adjustments, maintaining a diversified portfolio is essential for long-term financial health.
Stay informed on upcoming Bank of Canada announcements regarding future interest rate decisions. Understanding the central bank’s policy direction will help you make more informed decisions about when to enter or exit the market.
Frequently Asked Questions
Why did Canadian home sales fall in October 2026?
The decline was primarily driven by the Bank of Canada’s decision to raise the benchmark interest rate to 2.50%, which increased borrowing costs for prospective buyers.
Is the housing market in a total collapse?
No. While sales are down 10.6% year-over-year, seasonally adjusted sales saw a small month-over-month increase, suggesting the market is stabilizing rather than collapsing.
What is the outlook for the housing market in 2027?
RBC Economics suggests that strong population growth and a robust labour market may support a modest recovery in 2027, despite the current monetary headwinds.
Related reading: GTA Home Sales Drop 7.9 Percent Amid Market Hesitation, Bank of Canada Interest Rate Decision Lifts Target to 2.5 Percent, CMHC.