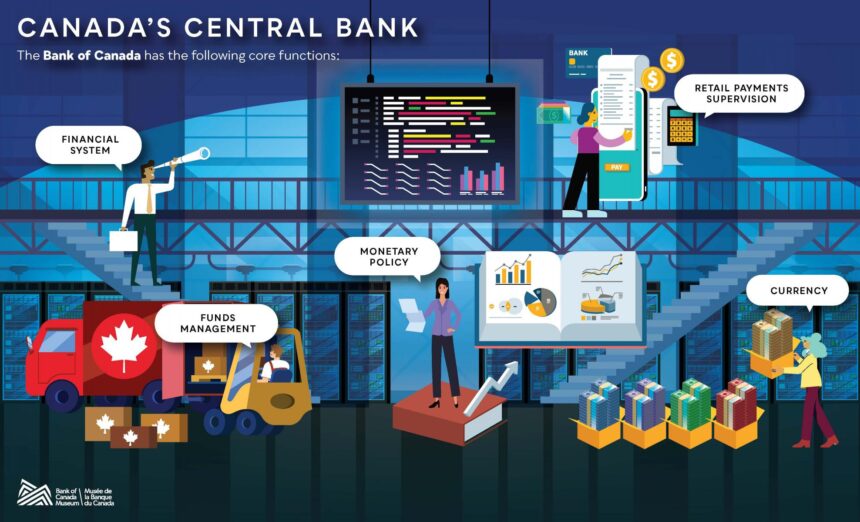
The Bank of Canada increased its policy interest rate to 2.5% on October 28, 2026, marking the first hike in three years. This shift in monetary policy arrives alongside an annual inflation rate of 3.1% recorded in September 2026.
This convergence of rising borrowing costs and stubborn price growth signals a challenging period for Canadian households. Launch Len Media views this transition as a critical test of the nation’s economic resilience against a backdrop of tightening financial conditions.
The stakes for the average consumer are high as debt servicing requirements climb. Policymakers now face the difficult task of balancing inflation control with the need to sustain modest growth.
The Bank of Canada Policy Shift
On October 28, 2026, the Bank of Canada moved to increase its benchmark policy interest rate to 2.5%. This decision ended a three-year period where the rate remained unchanged.
The move reflects concerns regarding persistent inflation, which stood at 3.1% in September 2026. Projections from the central bank suggest this rate will stay above 3% for much of 2027.
The decision by the bank of canada follows months of debate regarding the necessity of cooling the economy. Officials have indicated that elevated energy prices remain a primary driver of the current inflationary environment.
Economic growth remains constrained, with the Parliamentary Budget Officer projecting real GDP growth of only 0.9% for 2026. This limited growth potential complicates the central bank’s efforts to manage price stability without triggering a deeper downturn.
More Read
Housing Market and Mortgage Pressures
The Canadian housing market is currently navigating a period of downward price adjustment. According to the Canadian Real Estate Association, the national average home price fell 1.6% year-over-year to $666,538 in September 2026.
This decline occurs as higher borrowing costs reduce the purchasing power of prospective buyers. Many households are also facing the impact of mortgage renewals at significantly higher interest rates than those seen during the pandemic.
Mortgage arrears serve as a key indicator of financial stress within the housing sector. Data from the CMHC shows that Ontario’s mortgage arrears rate reached 0.32% in Q2 2026.
The CMHC expects these delinquency rates to rise further through mid-2027. This trend suggests that the financial buffer for many homeowners is thinning as monthly debt obligations climb.
Options for Navigating Financial Uncertainty
Households looking to manage their finances in a higher rate environment should prioritize debt consolidation and budget adjustments. The current economic climate requires a proactive approach to managing variable-rate debt.
Consider the following options for stabilizing your financial position during this period of economic volatility: Source: Canadian Real Estate Association via BNN Bloomberg.
Refinancing variable-rate mortgages into fixed-rate products may provide payment certainty for those concerned about future rate hikes. This strategy locks in current rates, protecting the borrower from further increases in the short term.
Building a larger emergency fund is essential as the cost of living remains high due to persistent inflation. Financial experts recommend maintaining at least six months of expenses in a liquid, high-interest savings account.
Reducing non-essential discretionary spending can help offset the impact of higher mortgage payments. By reallocating funds toward debt principal, homeowners can reduce their long-term interest exposure.
Consulting with a financial advisor can help clarify how specific investment portfolios might react to a 0.9% GDP growth environment. Diversification remains a primary tool for mitigating risk when the broader economy faces headwinds.
- Refinance variable-rate debt into fixed-rate terms for payment stability.
- Increase emergency savings to cover at least six months of living costs.
- Prioritize the repayment of high-interest consumer debt like credit cards.
- Review household budgets to identify and cut non-essential recurring expenses.
- Consult a professional to stress-test your portfolio against potential economic slowdowns.
Analysis of Economic Resilience
Launch Len Media maintains that the combination of rising interest rates and inflation creates a precarious situation for Canadian households. The risk of a broader financial contraction remains elevated as debt servicing costs consume a larger portion of disposable income.
However, some analysts point to the economy’s underlying resilience as a potential buffer against a crisis. Canada recorded its first current account surplus in four years in Q2 2026, totaling $8.8 billion, which provides some fiscal support.
The fair counterpoint is that the Bank of Canada’s measured approach may prevent a full-scale financial collapse. By moving in smaller increments, the bank aims to avoid shocking the system while still addressing inflationary pressures.
Despite this, the reality of a 0.9% growth projection suggests that the economy will remain fragile. The ability of households to absorb further rate increases will likely dictate the severity of the coming year. Source: CMHC.
The great mortgage shock of 2026 has not proven quite as ruinous as many feared it would be.
Dexter McMillan, The Globe and Mail
Next Steps for Readers
You should begin by auditing your current debt obligations to understand how a potential rate increase would affect your monthly cash flow. Knowing your exact interest rate and renewal date is the first step in effective planning.
If you are concerned about your mortgage, contact your lender to discuss potential renewal options well in advance. Many institutions offer flexibility for borrowers who demonstrate a clear plan for managing their payments.
Monitor your credit score to ensure you remain in a strong position for any necessary refinancing. Maintaining a good credit profile is essential when borrowing costs are high and lenders become more selective.
Finally, stay informed on future policy announcements from the Bank of Canada. Understanding the trajectory of interest rates will help you make more informed decisions about major purchases and long-term financial commitments.
Frequently Asked Questions
Why did the Bank of Canada raise interest rates?
The bank raised rates to combat persistent inflation, which remains elevated at 3.1% and is projected to stay above 3% through 2027.
Are Canadian home prices expected to keep falling?
National average home prices have already declined 1.6% year-over-year, and the current environment of higher interest rates may continue to exert downward pressure on the market.
What is the outlook for GDP growth in 2026?
The Parliamentary Budget Officer projects real GDP growth of 0.9% for Canada in 2026, indicating a period of slow economic expansion.