Finance Minister François-Philippe Champagne delivered the Federal Budget 2026 on November 5, 2026, prioritizing business investment and administrative tax simplification. The plan aims to stimulate long-term productivity while managing a projected $62.3 billion deficit for the 2026-27 fiscal year.
This budget represents a shift toward targeted growth incentives, though it leaves significant questions regarding the sustainability of the national debt. For taxpayers and business owners, understanding these new tax and retirement changes is essential for navigating the updated fiscal environment.
The Core Fiscal Framework and Spending
The 2026 federal fiscal plan, titled Masters of our destiny, outlines a total of $151 billion in new spending measures. According to CPA Canada chief economist David-Alexandre Brassard, this level of investment is intended to bolster the country’s economic foundation. Source: KPMG.
Despite the ambitious spending goals, the government faces a substantial deficit. KPMG reports that the projected shortfall for the 2026-27 fiscal year stands at $62.3 billion.
The budget attempts to balance these expenditures with growth-focused tax policies. By lowering the cost of capital for businesses, the government hopes to generate sufficient economic activity to offset the fiscal strain.
Critics argue that the reliance on high spending levels may exacerbate inflationary pressures. However, the government maintains that these investments are necessary to address structural productivity gaps.
Incentives for Business Investment
A central pillar of the budget is the Productivity Mega Deduction. This policy aims to reduce the marginal effective tax rate on new business investment from 13% to 6.4%, according to the official Canada.ca budget summary.
This reduction is designed to make Canada a more competitive destination for capital. By lowering the tax burden on new projects, the government expects to encourage firms to upgrade technology and expand operations.
The budget also expands the Scientific Research and Experimental Development (SR&ED) program. A $930 million investment will allow the program to include specific commercialization expenses, providing a broader base for innovation-related tax relief.
These measures are intended to address the long-standing issue of lagging productivity in the Canadian economy. By aligning tax incentives with commercialization, the government seeks to foster a more dynamic business environment.
Targeted Tax Exemptions and Options
The budget introduces specific tax-advantaged options for private corporations and investors. These tools are designed to unlock capital for growth-stage companies and encourage private sector participation.
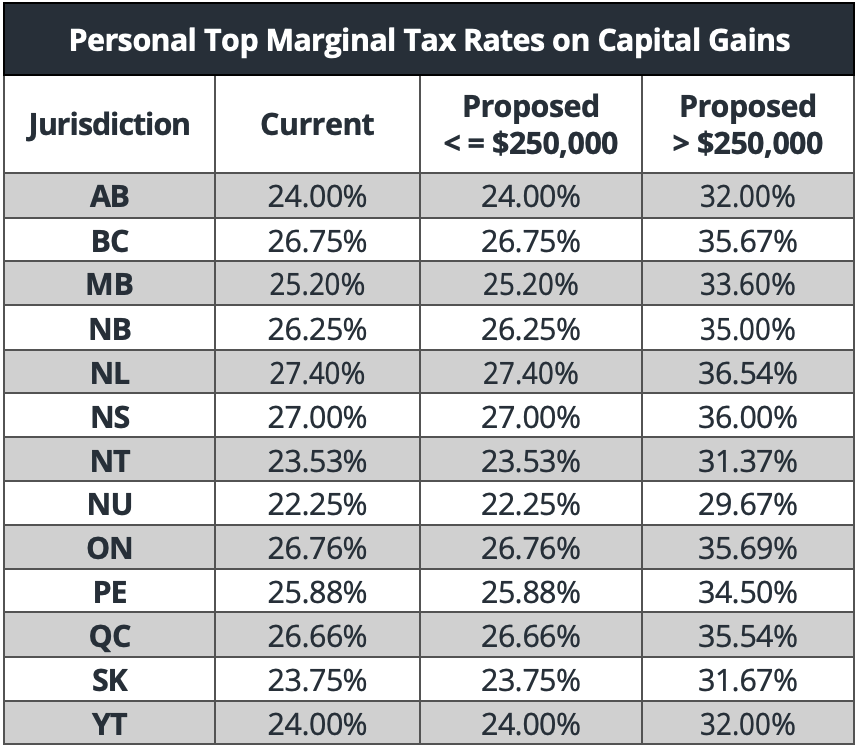
The Canada Growth Incentive provides a significant tax exemption on capital gains. This measure applies to up to $15 million in capital gains for eligible private corporation shares, as reported by Legal 500.
This incentive is aimed at entrepreneurs and early-stage investors who provide the necessary capital for business scaling. By reducing the tax friction on exits, the government hopes to increase the velocity of capital within the private market.
Investors should evaluate how these exemptions fit into their broader financial planning. While the incentive is attractive, it requires careful adherence to the eligibility criteria defined by the Canada Revenue Agency.
Administrative Changes for Taxpayers
The Federal Budget 2026 also streamlines the administrative process for personal income tax filings. These changes are intended to reduce the complexity of the tax system for individuals.
Personal income tax filing and payment deadlines are now consolidated to May 15, according to Global News. This change aims to provide a uniform timeline for taxpayers, simplifying the annual filing process.
The budget also increases instalment thresholds for individuals. This adjustment is expected to reduce the frequency of instalment payments for many taxpayers, further easing the administrative burden.
These updates represent a pragmatic approach to tax administration. By simplifying deadlines and thresholds, the government hopes to improve compliance and reduce the stress associated with tax season.
Analysis: Pragmatism Versus Structural Deficits
The 2026 budget represents a calculated bet on productivity-led growth. By focusing on the marginal effective tax rate, the government is addressing a key barrier to business investment, which is a sound economic strategy.
However, the fair counterpoint remains the scale of the deficit. A $62.3 billion shortfall in a single year raises questions about long-term fiscal sustainability, especially if the projected productivity gains do not materialize as expected.
Despite these risks, the focus on targeted incentives is likely more effective than broad-based tax cuts. The specific nature of the Canada Growth Incentive and the SR&ED expansion suggests a government that is attempting to be surgical with its fiscal policy.
The success of this budget will ultimately depend on whether the private sector responds to these incentives with increased investment. If businesses utilize the Productivity Mega Deduction to modernize, the long-term economic benefits could outweigh the short-term fiscal costs.
- Review your corporate investment plans to determine eligibility for the Productivity Mega Deduction.
- Consult with a tax advisor regarding the $15 million capital gains exemption under the Canada Growth Incentive.
- Update your personal tax planning calendar to reflect the new May 15 filing and payment deadline.
- Evaluate your current SR&ED claims to see if new commercialization expenses qualify for the expanded program.
- Monitor the impact of the $151 billion in new spending on broader economic indicators like inflation and interest rates.
The budget includes $151 billion in new spending measures.
David-Alexandre Brassard, CPA Canada Chief Economist
Frequently Asked Questions
What is the new filing deadline for personal income taxes? The new consolidated deadline for both filing and payment is May 15.
How much is the capital gains exemption for private shares? The Canada Growth Incentive allows for a capital gains exemption on up to $15 million for eligible private corporation shares.
What is the goal of the Productivity Mega Deduction? The goal is to lower the marginal effective tax rate on new business investment from 13% to 6.4% to boost economic productivity.