The Bank of Canada increased its policy interest rate to 2.5% on October 28, 2026, triggering a sharp rise in borrowing costs across the country.
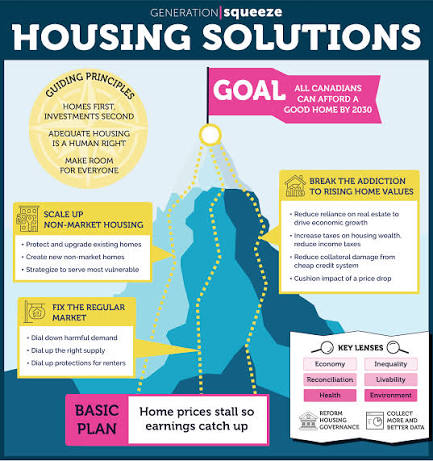
LaunchLen Media believes that aggressive housing policy reform is now the only viable mechanism to prevent a prolonged stagnation of new construction projects.
The stakes are high as developers face mounting financial pressure, potentially leaving thousands of families without new housing options.
The Impact of Rising Interest Rates
The Bank of Canada confirmed a 25 basis point hike to the policy interest rate on October 28, 2026. This move was intended to curb persistent inflation pressures that have challenged the national economy.
Following this announcement, major Canadian banks increased their prime lending rates to 4.70%. This adjustment directly impacts the cost of variable-rate mortgages and business loans for developers.
The Canadian Mortgage and Housing Corporation (CMHC) reported that housing starts in Ontario and British Columbia are expected to remain below their 10-year averages throughout 2026. High borrowing costs have made many projects financially unviable for developers.
The current environment creates a difficult paradox for policymakers. While high rates are necessary to control inflation, they simultaneously stifle the construction of new homes needed to address the ongoing supply crisis.
Government Strategy in Budget 2026
The federal government unveiled Budget 2026 on November 5, 2026, which includes a $30 billion commitment over 10 years to end homelessness. This initiative focuses heavily on the development of non-market housing.
In addition to funding, the government extended the Prohibition on the Purchase of Residential Property by Non-Canadians Act until January 1, 2029. This policy aims to keep residential inventory available for domestic buyers.
The Canadian Alliance to End Homelessness (CAEH) has publicly supported these budget commitments. They argue that the focus on non-market housing is a necessary step to protect vulnerable populations during economic volatility. Source: CBC News.
However, critics suggest that while non-market housing is important, it does not address the broader need for market-rate supply. The reliance on government spending may not be enough to stimulate the private sector development required to meet long-term demand.
Recommended Policy Reforms
To stabilize the market, experts suggest that governments must move beyond simple funding and address structural barriers. These reforms are designed to lower costs and speed up the delivery of new units.
The following list outlines key areas for reform that could help mitigate the impact of high interest rates on the construction sector.
These measures focus on increasing the efficiency of the development process to ensure that projects remain profitable despite higher financing costs.
- Implement comprehensive zoning deregulation to allow for higher density in urban centers.
- Provide tax incentives specifically for the construction of family-sized housing units.
- Streamline municipal permitting processes to reduce the time between project approval and groundbreaking.
- Expand infrastructure grants to support the development of serviced land in suburban areas.
- Introduce temporary relief measures for developers facing liquidity challenges on active projects.
Analysis of the Current Market Stance
The argument for aggressive housing policy reform rests on the idea that supply is the primary driver of affordability. By reducing the regulatory burden, provinces can encourage developers to maintain momentum even when borrowing is expensive.
Conversely, some analysts warn that aggressive intervention during a period of monetary tightening could be risky. They argue that if the government forces supply into a market where demand is suppressed by high rates, it could lead to an oversupply of specific housing types. Source: Government of Canada.
This could result in financial losses for developers and a potential decline in market confidence. Critics suggest that a more cautious approach, focusing on targeted support rather than broad deregulation, might be safer.
Despite these concerns, the persistent shortfall in housing starts suggests that the status quo is failing. Without systemic changes, the gap between supply and demand will likely continue to widen, keeping prices elevated for the average Canadian.
The federal government committed nearly $30 billion in Budget 2026 to a 10-year plan aimed at ending homelessness.
Government of Canada
Next Steps for Market Participants
If you are involved in the housing market, you should monitor local zoning changes closely. Municipalities are increasingly under pressure to align with provincial targets, which may create new opportunities for development.
Investors and homeowners should also be aware of the implications of rising rates on their existing debt. Reviewing your financial position regarding mortgage renewals is essential as rates remain elevated.
For those looking for affordable housing units, keep an eye on government-funded projects in your region. These developments are often prioritized in the current budget cycle and may offer more stability than private market options.
Finally, stay informed about provincial housing policy reform initiatives. These changes will likely dictate the pace of construction and the availability of new inventory in the coming years.
Related coverage on LaunchLen Media: Bank of Canada Interest Rate Decision Lifts Target to 2.5 Percent.
Frequently Asked Questions
How does the interest rate hike affect housing construction?
Higher interest rates increase the cost of financing for developers, which makes many new construction projects less profitable or entirely unviable.
What is the status of the foreign buyer ban?
The federal government has extended the Prohibition on the Purchase of Residential Property by Non-Canadians Act until January 1, 2029, to help manage market demand.
What is the focus of the $30 billion commitment in Budget 2026?
The funding is part of a 10-year plan specifically aimed at ending homelessness through the development of non-market housing.