The Bank of Canada increased its benchmark interest rate by 25 basis points to 2.5% on October 28, 2026, marking the first hike since July 2023. This move signals a shift in monetary policy as officials attempt to curb inflation driven by global energy prices.
Launch Len Media believes this environment necessitates a pivot for TFSA investors who have relied on passive cash holdings. Moving toward dividend-growth assets can help protect purchasing power against the projected 3.5% inflation rate by the end of 2026.
The Bank of Canada Policy Shift
Bank of Canada Governor Tiff Macklem announced the rate increase on October 28, 2026, citing the need to prevent energy-driven inflation from becoming entrenched. The central bank expects inflation to average 3% throughout 2027.
The move to 2.5% represents a departure from the previous period of stability. According to data from the Canada Revenue Agency, the 2026 annual contribution limit for a TFSA is $7,000, with a maximum cumulative room of $109,000 for eligible individuals.
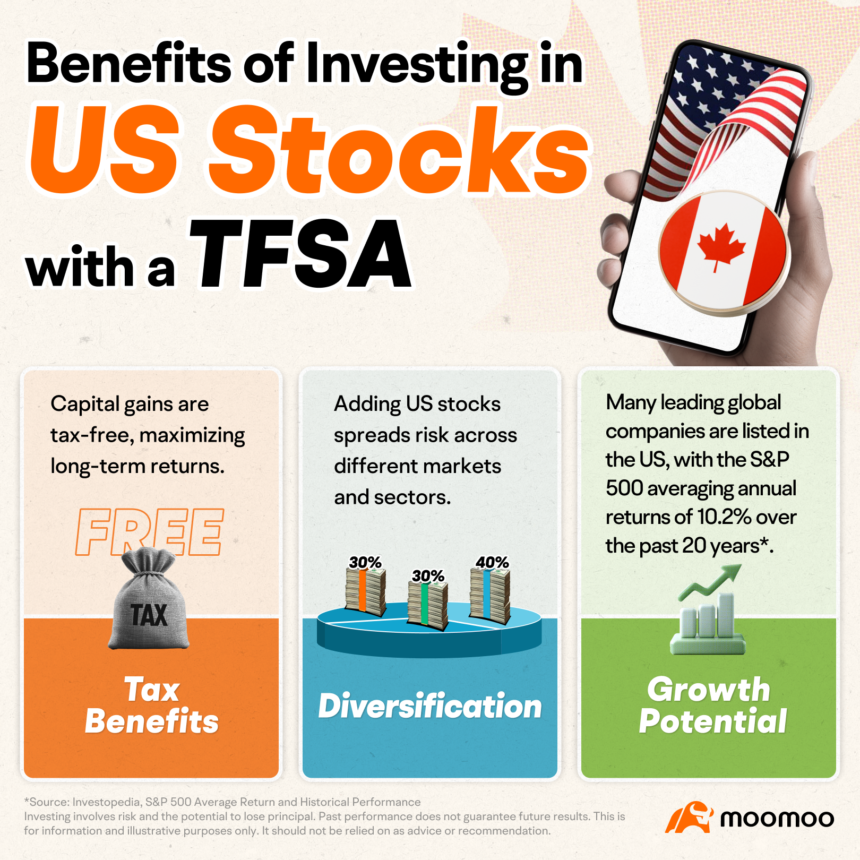
For many Canadians, the TFSA serves as a primary vehicle for long-term savings. The combination of tax-free growth and the ability to re-contribute withdrawn funds starting January 1 of the following year makes it a flexible tool for navigating changing interest rate cycles.
While high-interest savings accounts and GICs offer capital protection, they may struggle to outpace the projected inflation rate. Investors must weigh the safety of these instruments against the potential for long-term wealth erosion.
Mechanics of Dividend Growth Investing
Dividend-growth investing focuses on companies that consistently increase their payouts to shareholders. This strategy often serves as a hedge against inflation because successful companies can raise prices and pass earnings to investors.
Financial institutions often benefit from higher interest rates through improved net interest margins. However, the actual impact depends on deposit costs and lending demand. Analysts suggest that investors look for companies with a proven track record of dividend increases over the last decade.
Earnings growth is a critical metric for evaluating these stocks. Companies expected to grow earnings per share by at least 8% annually are generally considered strong candidates for long-term holding. This growth provides the foundation for sustainable dividend increases.
Investors should also consider the valuation of these companies. Buying shares at a fair price is essential to achieving expected returns. Accumulating positions gradually, especially during market pullbacks, can lower the average cost basis over time.
The key is not simply betting on higher interest rates. It is owning quality businesses capable of delivering sustainable earnings and dividend growth at reasonable valuations.
The Motley Fool Canada
Top Financial Sector Candidates
Royal Bank of Canada (TSX: RY) stands out as a primary candidate for a diversified TFSA portfolio. With a dividend yield of approximately 2.4% and a 15-year dividend growth rate of 7.6%, it offers a blend of stability and income. Source: The Motley Fool Canada.
The bank has demonstrated significant performance, with shares rising 244% over the past three years. While chasing past performance is discouraged, its diversified operations and competitive advantages remain strong pillars for long-term investors.
Sun Life Financial (TSX: SLF) presents an alternative within the financial sector. As a leading insurer, it benefits from higher yields on its fixed-income investments, which are used to back policyholder reserves.
Sun Life offers a dividend yield of nearly 3.3% and a 10-year dividend growth rate of 8.8%. Analysts view the company as fairly valued, making it a potential addition for investors seeking consistent income streams in a volatile market.
Both stocks are projected to achieve annual returns of 10% to 11% if earnings growth forecasts materialize. These figures include dividends and assume that current valuation multiples remain relatively stable.
- Royal Bank (TSX: RY): Strong balance sheet with a 7.6% long-term dividend growth rate.
- Sun Life (TSX: SLF): Benefits from higher reinvestment yields on fixed-income assets.
- Diversification: Combining financial stocks with other sectors helps mitigate specific industry risks.
- Gradual Accumulation: Buying on market pullbacks improves the long-term entry price for TFSA investors.
- Quality Focus: Prioritize companies with earnings growth that comfortably exceeds the inflation rate.
Analysis of the Investment View
Launch Len Media maintains that shifting toward dividend-growth stocks is a logical response to the current inflation outlook. Relying solely on cash or GICs may result in a decline in real purchasing power as inflation reaches 3.5%.
A fair counterpoint is that cash and GICs provide essential capital preservation. For investors with short-term financial goals, such as a home purchase or an upcoming expense, the volatility associated with equity markets may be unacceptable.
Maintaining a portion of your TFSA in cash is not an admission of defeat. It is a strategic choice that provides the liquidity needed to capitalize on market corrections when high-quality stocks become available at a discount.
The goal is to strike a balance. By holding a core of dividend-growth stocks, investors can participate in the long-term success of Canadian businesses while retaining enough cash to manage short-term risks. Source: Global News.
Next Steps for TFSA Investors
Review your current TFSA holdings to determine how much of your capital is sitting in low-yield cash accounts. Calculate the real return after accounting for the projected 3.5% inflation rate.
Research the dividend history of companies you are considering. Look for a track record of consistent increases and a manageable payout ratio that indicates the dividend is sustainable.
Establish a plan for gradual investment. Rather than deploying all available cash at once, consider setting aside funds to purchase shares during market dips to improve your average cost.
Consult with a financial advisor if you are unsure about your risk tolerance. Ensuring your portfolio aligns with your long-term goals is the most important step in managing your TFSA effectively.
Frequently Asked Questions
Should I sell my GICs to buy stocks?
It depends on your time horizon. If you need the money within the next two years, keeping it in GICs is safer, but if you are investing for the long term, dividend stocks may offer better inflation protection.
How does the TFSA contribution limit affect my strategy?
The 2026 limit of $7,000 is a cap on new contributions. You should prioritize filling this space with your highest-quality, long-term growth assets to maximize the tax-free compounding effect.
Is it better to hold cash or stocks in a rising rate environment?
Cash provides liquidity and safety, while stocks provide the potential for growth. A balanced approach allows you to benefit from interest income while protecting against the erosion of purchasing power.